A Wetlands Permit Underwrites the $70 Million AMP Robotics Project Financing
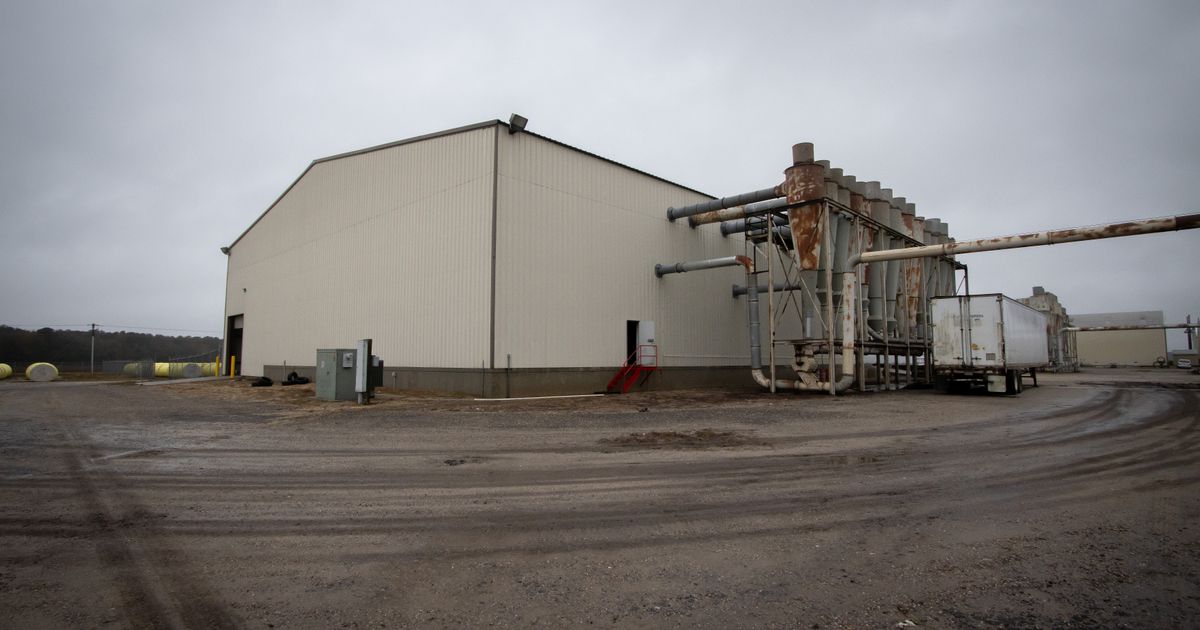
On October 1, AMP closed $70 million in project debt led by Galvanize to pay for a second sortation line and an organics plant in Portsmouth, Virginia, according to Recycling Today. Every write-up leads with the machinery: AI cameras, robotic pickers, pneumatic jets, sealed garbage bags going in the front end with nobody at home separating anything. Fine. But if you're reading the AMP Robotics project financing as a template for your own region, what Galvanize took as security tells you more than what AMP installed.
I've spent thirty years on the deal side of manufacturing and environmental ventures, and one pattern never changes. The press release describes the plant. The credit agreement describes the counterparty. Here the counterparty is a Virginia public authority whose landfill is filling up.
The borrower's credit is a public authority's airspace problem
SPSA's board approved a twenty-year processing contract with Commonwealth Sortation, an AMP affiliate, in November 2025, covering roughly $200 million of sorting services and infrastructure for eight Hampton Roads localities and 1.2 million residents, per AMP's announcement of the award. At full scale the regional system is meant to take more than half a million tons a year of raw, unsorted household and commercial waste. Elected boards don't hand over two decades of tonnage because a demonstration impressed them. They do it when the alternative looks worse.
SPSA's Regional Landfill in Suffolk is that alternative. Cells five and six held about 1.8 million cubic yards of remaining airspace going into 2024, tracking to fill in April 2027. Then at the February 2024 board meeting the authority's executive director moved the depletion date in to December 2026, an airspace forecast that missed by four months inside a single budget cycle, as reported by the Smithfield Times. A revision like that moves a procurement from study to urgent.
What comes next is federal. SPSA has asked the Army Corps of Engineers' Norfolk District for an individual permit under Section 404 of the Clean Water Act to fill 109.64 acres of forested wetlands and open cells VIII and IX, roughly 16 million cubic yards of new airspace, with the Corps publishing its final environmental impact statement in March 2025. So the host authority's fallback sits with a federal regulator, on a timetable it can't set.
That's the security package. A twenty-year delivery obligation is worth exactly as much as the counterparty's shortage of options, and SPSA is short on options. Own the feedstock or you don't own the project. And AMP doesn't own this feedstock. What it owns is a two-decade claim on somebody else's, pinned in place by that somebody having no cheap exit. In waste, that's about as close to ownership as anyone gets.
Three revenue lines, and debt sizes against one
Strip the project to its cash flows and three things pay for it.
- A contracted gate fee. SPSA held its municipal tipping rate at $65/ton for fiscal 2026, so there's a public benchmark for what the region pays to make a ton disappear. Twenty years, a public counterparty, escalators in the contract. This is the line a lender can model.
- Recovered commodities. The agreement guarantees twenty percent recovery as recyclables, which is a performance covenant. Nothing in it guarantees what a ton of mixed-stream PET or baled aluminum clears in 2031. Merchant risk, end to end.
- Carbon. In March 2026 Google agreed to buy 200,000 tons of carbon removal generated by AMP's organics processing by 2030, as ESG Dive reported. Creditworthy buyer, real tenor, and wholly contingent on the organics line hitting its numbers.
A lender sizes senior debt against the first and calls the other two equity upside. Money goes where a counterparty is obliged to deliver a volume it already controls, and only the gate fee qualifies. Everything else is a forecast wearing a contract.
I had this backwards for most of my career. I priced projects off the output, the megawatt or the recovered ton, and treated the gate fee as a helpful offset. Wrong end of the business. The gate fee is the product and the recovered material is the byproduct, and pricing it the other way around is how sound projects die at financial close. The best hedge in waste is a long-term supply contract, not a swap.
Thirty percent organics is the covenant that can slip
Fifty percent landfill diversion is the headline. Underneath it splits into twenty percent recyclables and thirty percent organics, and those halves aren't equally hard. Metals and rigid plastics out of raw trash is a solved problem at this point, and optical units and robotic pickers have been doing it at commercial throughput for years. But organics out of a sealed bag is messier. You get a wet fraction carrying glass fines and film, and whatever runs downstream of it has to tolerate that every shift.
According to EPA's national materials figures, food waste alone runs to 63.1 million tons a year, close to a fifth of everything generated, with roughly half of all tonnage still buried. That's the prize.
AMP's answer is indirect heating to biochar, with the char going initially to daily cover at a landfill. The first market for the material is therefore cost avoidance at the same landfill the project exists to divert from. Nobody's selling it into cement or agriculture yet (those get listed as future uses, which in my experience means somebody still has to qualify the material against a spec). Revenue comes from the credit rather than the char, which is a defensible structure and a narrow one: it leans on a voluntary buyer's continued appetite, and on the receiving landfill's permit accepting the material as alternative daily cover inside the Subtitle D criteria at 40 CFR Part 258.
Then there's measurement. A diversion covenant is a mass-balance claim, and mass-balance claims get audited by people who weren't on site. I built Haultail around the premise that a load you can't verify is a load you can't bill for, and the same applies here: inbound scale tickets, residue tonnage out the back, moisture-corrected organics mass, reconciled monthly instead of annually. Lenders on this kind of deal verify the measurement chain before the technology, and decent waste intelligence software earns its keep in that reconciliation.
Where the Portsmouth structure doesn't travel
Four conditions make AMP Robotics project financing work in Hampton Roads, and most regions miss at least one of them.
You need a host with a near-term airspace cliff. An authority sitting on thirty years of permitted capacity has no reason to commit its stream for twenty. You need a public body that genuinely controls the tonnage, because in open-market states a county can promise delivery it has no power to compel, and a lender discounts that promise to near zero. You need gate fees with room in them (SPSA isn't an expensive disposal market by national standards, and a region clearing half its rate has nothing to work with). And you need scale: at better than 1,400 tons each day the fixed cost of bag opening, screening and a Tomra-class optical front end spreads thin. At two hundred it doesn't.
Scale-up risk needs its own line in the model. The existing Portsmouth plant handles roughly 108,000 tons a year; the contracted system is designed for 540,000. That's a fivefold step on a process whose hardest fraction, the organics, hasn't run at the bigger number. Does the recovery curve hold when the belt speed goes up and the feed gets wetter? Nobody knows yet, which is one reason the debt is sized where it is.
The carbon leg has its own gate. A buyer of Google's size and credit quality doesn't turn up for every project, and if your organics offtake is a regional compost market instead of a corporate removal contract, you're financing a different business with a different debt capacity. Anyone benchmarking against this deal while shopping waste-to-energy technology for a smaller host should price that gap in early.
The documents to pull before you price one of these
Ask the host authority for its two most recent annual airspace surveys and the dates its board accepted each, then set the depletion dates side by side. Four months of slippage between consecutive surveys will tell you more about how that authority negotiates than any sortation demonstration will. Pull the permit docket for whatever expansion is pending, which in Virginia means a Corps file that's been open since 2020. Read the delivery clause in the draft agreement and find out whether it says put-or-pay or best efforts. Those three documents set the debt capacity; the equipment list only sets the capex. So anyone treating AMP Robotics project financing as the comparable for their own market should start there, well before the vendor shortlist.
Across the waste conversion facilities that reached financial close over the last five years, the ones that got built tended to have a host with nowhere else to put its garbage. Before anything else, establish on paper whether yours is in that position, because that single fact decides whether waste infrastructure project debt is available at all.
Disclosure: I'm CEO of The Waste Agency and write on waste-to-energy and carbon-market commercialization for Renewable Waste Energy.
Sources & Notes
- Financing terms, closing date and facility scope come from Recycling Today's October 1, 2026 report, with BizWest covering the same close.
- Contract length, the member localities and the twenty-thirty diversion split are drawn from AMP's own statement on the SPSA award. Read those as contract targets rather than measured performance.
- On the landfill: the airspace revision presented at SPSA's February 2024 board meeting was reported by the Smithfield Times. Acreage, cell numbering and the EIS date for the pending expansion sit in the Norfolk District's Section 404 permit file.
- Google's removal purchase was reported by ESG Dive in March 2026. Neither party disclosed a price per ton, so any implied carbon revenue is your own assumption.
- For the national picture on what gets buried and how much of it is food, see EPA's materials and waste figures, which lag the present by several years.
Researched and written by OWI editorial staff. Technical review by RWE engineering. AI tools used for drafting assistance.
Cite this article
Alex Mardikian, “A Wetlands Permit Underwrites the $70 Million AMP Robotics Project Financing,” Optimal Waste Intelligence, October 05, 2026, https://optimalwasteintelligence.com/posts/amp-robotics-mixed-waste-sorting-project-finance.
You’re welcome to quote this article with attribution and a link to the original.